Custom HBM+CoWoS Portfolio: The DIY Index Construction
Thematic ETFs are convenient, but they're also blunt instruments. An AI infrastructure ETF might give you exposure to HBM (high-bandwidth memory) and CoPoS (co-packaged optics) leaders, but it'll also dump you into NVIDIA, Broadcom, and a dozen other names that dilute the pure play.
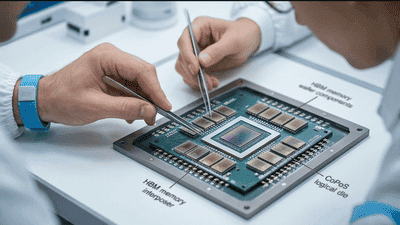
This post walks through constructing a custom HBM+CoPoS portfolio from scratch. We'll identify the constituent names, determine weighting methodologies, discuss implementation vehicles (equities, ETFs, index derivatives), outline rebalancing rules, and address risk management. The goal is practical: not just understanding what HBM and CoPoS are, but how to build a tradable, investable index that captures the theme without the baggage of off-the-shelf ETFs.
Defining the HBM+CoPoS Universe
Before building the index, you need to define the universe. HBM and CoPoS are distinct technologies, but both are critical to AI computing infrastructure. HBM is stacked DRAM that provides high-bandwidth memory for AI accelerators (GPUs, TPUs, custom AI chips). CoPoS integrates optical transceivers directly with ASICs or GPUs, reducing power consumption and latency in AI data centers. Together, they represent the memory and interconnect bottlenecks in AI infrastructure.
HBM Supply Chain
The HBM value chain spans DRAM makers, equipment suppliers, and packaging specialists:
- DRAM Manufacturers: SK Hynix (market leader in HBM3E, HBM4), Samsung (aggressive HBM ramp, supplying NVIDIA and others), Micron (HBM3E sampling, targeting 2026 volume). These three control 95%+ of HBM production.
- Equipment Suppliers: ASML (EUV lithography for DRAM patterning), Tokyo Electron (deposition, etch for DRAM), Lam Research (etch for high-aspect-ratio TSVs), KLA (metrology for DRAM yields), Disco (dicing, grinding for thin DRAM dies).
- Packaging & Testing: Amkor Technology (advanced packaging for HBM modules), JCET (Chinese packaging, HBM exposure), Siliconware (ASE Group subsidiary, HBM packaging). TSMC also packages HBM with CoWoS, but it's a smaller portion of revenue.
CoPoS Supply Chain
The CoPoS value chain spans optical component makers, ASIC designers, and integration specialists:
- Optical Component Makers: Broadcom (leading CoPoS provider, supplying Google TPUs and custom AI chips), Marvell (PAM4 DSPs, optical engines for CoPoS), Lumentum (lasers, optical components), II-VI (now Coherent, optical materials and components), Finisar (VF Corporation, optical engines).
- ASIC & Switch Makers: NVIDIA (integrating CoPoS in GB200, Rubin platforms), AMD (MI350, MI400 with CoPoS options), Intel (Gaudi3, future AI ASICs with CoPoS), Cisco (Silicon One switches with CoPoS), Arista (7800R3 series with CoPoS).
- Integration & Substrate: Ibiden (substrate for CoPoS modules), Shinko (substrate supplier), NGK (ceramic substrates), ASE Group (system-in-package integration).
Overlap and Purity
Some names appear in both HBM and CoPoS (e.g., TSMC, ASE Group, Broadcom). Others are pure-play (SK Hynix for HBM, Lumentum for CoPoS). For a custom index, decide whether to include overlap names once (weighted by combined exposure) or exclude them to maximize purity. The latter approach—favoring pure-play names—creates a cleaner thematic bet but reduces diversification.
Weighting Methodologies
Once you have the universe, you need to weight the constituents. Three common approaches:
Equal Weight
Simplest method: each name gets the same weight (e.g., 5% each in a 20-name index). Pros: maximum diversification, no single-name risk. Cons: dilutes high-conviction names, includes low-purity names at same weight as leaders.
Best for: investors who want broad thematic exposure without taking strong views on individual names. Suitable for core holdings, not tactical overlays.
Revenue-Weighted
Weight names by estimated HBM or CoPoS revenue exposure. For example, if SK Hynix derives 25% of revenue from HBM and Lumentum derives 15% from CoPoS, weight accordingly. Pros: aligns weights with thematic purity, favors market leaders. Cons: requires revenue estimates (often unavailable or unreliable), can concentrate risk in a few names.
Best for: investors who have proprietary research on revenue exposure and want to maximize thematic beta. Suitable for satellite positions, not core holdings.
Market Cap-Weighted (with Caps)
Weight names by market capitalization, but cap individual weights (e.g., no name above 15%). Pros: reflects market pricing, liquid, easy to implement. Cons: large-cap names (NVIDIA, Broadcom) dominate, diluting pure-play exposure.
Best for: investors who want thematic exposure but with liquidity and stability. Suitable for core holdings, especially if using ETFs or index derivatives.
For a HBM+CoPoS index, a hybrid approach works best: revenue-weighted for pure-play names (SK Hynix, Lumentum, Marvell), equal-weight for overlap names (TSMC, ASE), and exclude broad-market names (NVIDIA, Broadcom) unless HBM/CoPoS exposure exceeds 20% of revenue. This balances purity, diversification, and implementability.
Implementation Vehicles
Once you've defined the universe and weighting, you need to implement the index. Several vehicles are available, each with tradeoffs:
Direct Equity
Buy the underlying stocks in the target weights. Pros: maximum control, no tracking error, transparent. Cons: transaction costs (especially for KRW-listed SK Hynix, Samsung), rebalancing friction, currency risk for non-USD names.
Best for: institutional investors with prime brokerage access, low trading costs, and multi-currency capabilities. Retail investors can do this too, but friction is higher.
Single-Name ETNs/ETFs
Some European and Asian exchanges offer single-name ETNs on SK Hynix, Samsung, TSMC, etc. Pros: USD-denominated, exchange-traded, no prime brokerage needed. Cons: limited availability, tracking error, fees (20-50 bps).
Best for: retail investors or small institutions without direct market access. Use for names that are hard to trade directly (KRW, TWD-listed).
Custom Basket Swaps
Prime brokers offer custom basket total return swaps. You specify the constituents and weights; the swap counterparty delivers the return. Pros: no transaction costs on rebalancing, securities lending revenue, customizable. Cons: counterparty risk, fees (10-30 bps), minimum notional ($5-10 million).
Best for: institutional investors with $10 million+ to deploy, seeking tax efficiency and low friction. Not suitable for retail or small accounts.
Index Derivatives + Overlay
Use broad semiconductor index derivatives (SOX futures, SMH options) and overlay single-name longs/shorts to tilt toward HBM+CoPoS. For example, long SOX futures + long SK Hynix ETN + long Lumentum - short NVIDIA (to reduce broad semi beta). Pros: liquid, capital efficient, hedgable. Cons: tracking error, complexity, basis risk.
Best for: tactical investors who want to express HBM+CoPoS views without full notional deployment. Suitable for satellite positions, overlays, or hedging.
Thematic ETFs (Proxy)
Some thematic ETFs have meaningful HBM or CoPoS exposure (e.g., AI infrastructure ETFs, semiconductor equipment ETFs). Pros: liquid, exchange-traded, no customization needed. Cons: dilution (many ETFs include NVIDIA, AMD, etc.), fees (40-75 bps), limited pure-play exposure.
Best for: investors who want convenience over purity. Use as a starting point, then overlay single names to increase thematic beta.
For most investors, a mix works best: direct equity for liquid, USD-listed names (Micron, Lumentum, Marvell); single-name ETNs for KRW/TWD-listed names (SK Hynix, Samsung, TSMC); and index derivatives for beta management. This balances control, cost, and implementability.
Rebalancing Rules
Thematic indices drift. HBM leaders become CoPoS laggards. Revenue exposure shifts. Market caps oscillate. Rebalancing keeps the index aligned with the theme. Key considerations:
Rebalance Frequency
Quarterly: Standard for most thematic indices. Aligns with earnings season, when revenue exposure updates. Pros: captures fundamental shifts, manageable friction. Cons: can be too slow for fast-moving themes like HBM/CoPoS.
Semi-Annually: Less friction, but risks drift. Suitable for more stable themes, not HBM/CoPoS where technology transitions happen quickly.
Monthly: Captures momentum, but high friction. Only suitable for liquid, low-cost portfolios (e.g., ETF-based, not single-name equities).
For HBM+CoPoS, quarterly rebalancing is optimal. Rebalance in January, April, July, October—after earnings season, when revenue guidance is fresh.
Rebalance Triggers
Besides calendar-based rebalancing, use trigger-based rebalancing:
- Weight Drift: If any name drifts more than 25% from target weight (e.g., a 10% target becomes 12.5% or 7.5%), rebalance that name.
- Thematic Purity: If a name's HBM/CoPoS revenue exposure falls below 10% (e.g., due to M&A or business mix shift), remove it from the index.
- Liquidity: If a name's average daily volume falls below $50 million (for direct equity) or bid-ask spreads widen above 50 bps, reduce weight or remove.
- Valuation: If a name's P/S or P/E exceeds 3 standard deviations from the index median, trim weight (mean reversion signal).
Rebalancing Process
Step-by-step:
- Review Constituents: Assess each name's HBM/CoPoS exposure based on latest earnings, analyst reports, and industry data. Add new names (e.g., emerging HBM startups, CoPoS integrators), remove names with declining exposure.
- Recalculate Weights: Apply the weighting methodology (revenue-weighted, equal-weight, or hybrid) to the updated universe. Ensure no single name exceeds the cap (e.g., 15%).
- Trade to Target: Execute trades to align portfolio weights with target weights. Use limit orders, VWAP algorithms, or block trades to minimize slippage.
- Document Changes: Record additions, deletions, and weight changes. Maintain a versioned index methodology for transparency and auditability.
Risk Management
Custom indices carry specific risks. Manage them explicitly:
Concentration Risk
HBM is dominated by SK Hynix, Samsung, Micron. CoPoS is dominated by Broadcom, Marvell, NVIDIA. A pure-play index can be highly concentrated. Mitigate by capping individual weights (10-15% max), diversifying across HBM and CoPoS (50/50 or 60/40 split), and including equipment/packaging names (ASML, Tokyo Electron, ASE) for indirect exposure.
Technology Risk
HBM and CoPoS are evolving technologies. HBM4 may displace HBM3E. CoPoS may lose to CPO (co-packaged photonics) or alternative interconnects. Monitor technology roadmaps (JEDEC standards for HBM, OIF standards for CoPoS), and adjust the index if technology shifts threaten constituent exposure.
Geopolitical Risk
SK Hynix (Korea), Samsung (Korea), TSMC (Taiwan), and Chinese packaging names (JCET) face geopolitical risk—U.S.-China tensions, Korea-China trade disputes, Taiwan Strait risk. Mitigate by diversifying across geographies (U.S., Europe, Japan, Taiwan, Korea), and hedging currency risk (KRW/USD, TWD/USD forwards).
Liquidity Risk
Some names (especially KRW-listed SK Hynix, Samsung) have lower liquidity than U.S. names. Size positions to avoid slippage. Test exit liquidity before entering—can you unwind the position in 1-2 days without moving the market? Use ETNs or ADRs for less liquid names.
Correlation Risk
HBM and CoPoS names can correlate highly during broad market selloffs (e.g., 2022 tech crash). Hedge with broad semiconductor index puts (SOX puts, SMH puts) or VIX calls to protect against systemic risk. Don't let a thematic index become a beta proxy.
Performance Attribution
Once the index is live, track performance attribution. Decompose returns into:
- Thematic Beta: Return from HBM/CoPoS exposure (vs. broad semiconductor index).
- Security Selection: Return from picking winners within HBM/CoPoS (e.g., SK Hynix vs. Samsung).
- Weighting Alpha: Return from weighting methodology (revenue-weighted vs. equal-weight vs. market cap).
- Rebalancing Alpha: Return from rebalancing discipline (buying low, selling high on quarterly rebalances).
This decomposition tells you what's driving returns. If thematic beta is strong but security selection is weak, you're capturing the theme but picking the wrong names—consider broadening the universe or using equal-weight. If weighting alpha is negative, your methodology is flawed—revisit the weighting scheme.
The Bigger Picture
DIY index construction is more than a portfolio exercise. It's a framework for thinking about thematic investing. Instead of buying an ETF and hoping the manager picks the right names, you're forced to understand the supply chain, assess revenue exposure, and make explicit weighting decisions. This discipline compounds: over time, you build a mental model of the theme that off-the-shelf ETF investors never develop.
For HBM+CoPoS, this matters. These are fast-evolving technologies. Today's leaders (SK Hynix, Broadcom) may be tomorrow's laggards. Today's bottlenecks (HBM capacity, CoPoS integration) may be tomorrow's commoditized components. By building your own index, you stay engaged with the theme—monitoring earnings, tracking technology roadmaps, and adjusting exposure as the landscape shifts.
The payoff is asymmetric. When you're right, you capture pure thematic beta without dilution. When you're wrong, you learn faster—because you built the index, you understand why it underperformed, and you can adjust. Over full cycles, this discipline compounds into alpha.
Final Thoughts
Custom HBM+CoPoS portfolio construction isn't for everyone. It requires work: researching constituents, estimating revenue exposure, implementing trades, rebalancing quarterly, managing risk. But for investors who want concentrated exposure to AI storage and computing—without the baggage of broad-market ETFs—it's the best solution available.
The framework outlined here is a starting point, not a prescription. Adjust the universe, weighting, rebalancing, and risk management to fit your constraints, conviction, and capacity. The goal isn't perfection—it's improvement over off-the-shelf alternatives.
HBM and CoPoS will continue to evolve. New names will emerge. Old names will fade. Technology will shift. And through it all, investors who own their index—rather than renting someone else's—will have the flexibility to adapt.
The theme is clear. The constituents are identifiable. The framework is actionable. Build.